
Serving Woodstock, Ontario
Mortgage Broker in Woodstock, Ontario
Pre-approvals, purchases, renewals and refinancing for Woodstock and Oxford County, compared across 50+ lenders, including plant overtime, trades income and rural properties.
- FSRA licensed agent
- 50+ lenders compared
- MBA in Finance
- Based in London, ON
Woodstock at a glance
- Population
- About 47,000 (2021 Census)
- Region
- Oxford County seat, where the 401 meets the 403
- Drive to London
- About 40 minutes
- Major employer
- Toyota's TMMC plant, which builds the RAV4
- Municipal land transfer tax
- None, provincial tax only
- Housing mix
- Century homes downtown, post-war bungalows, newer subdivisions
Sources: Statistics Canada 2021 Census (population 46,705); Toyota Motor Manufacturing Canada. Your own approval depends on your file, not the town.
Today's Lowest Rates · Woodstock
As of October 23, 2026
- Fixed
- 4.34%
- 5-Year term
- Variable
- 3.43%
- 5-Year term
- Prime
- 4.45%
- Bank of Canada
Rates are set by lenders, not by town, and depend on your own file.
Compare all 8 terms & inquire
Woodstock, Ontario — Daily Update
Compare Today's Mortgage Rates
As of October 23, 2026
Bank of Canada overnight rate 2.25%, prime 4.45%
2-Year
Fixed
4.39%
Big 6 Bank
Variable
—
3-Year
Fixed
4.49%
Canadian Lender
Variable
3.90%
Alterna Savings
5-Year
Fixed
4.34%
Canadian Lender
Variable
3.43%
Canadian Lender
Rates shown are for insured mortgages (down payment under 20%). Conventional/uninsured pricing may differ — contact me for your exact rate.
Rates are illustrative, change daily and are subject to lender qualification. Source: Ratehub.ca public rate table, as of October 23, 2026.
Mortgage services for Woodstock clients
Swipe for more services →
Access to 50+ lenders — banks, credit unions and mortgage lenders




Big banks · Credit unions · Mortgage lenders
+ 40 more, compared for youBuying or renewing in Woodstock
Woodstock is the county seat of Oxford County, sitting where Highway 401 meets Highway 403 — about 40 minutes from London. That crossroads position shapes the files I see here: commuters priced out of larger centres, local manufacturing and trades households, and owners with long-held equity in older in-town homes.
Woodstock is the county seat of Oxford County, and its housing runs from century homes near the downtown to post-war bungalows and newer subdivisions on the edges of the city. Its position where the 401 and 403 meet makes it a practical base for people who work across the region.
Many buyers here work in manufacturing, including at the Toyota plant and its suppliers, or commute along the 401 and 403. Shift premiums, overtime and probation periods are common in these files, and homeowners renewing often want to compare a lender switch or consolidate debt.
Mortgage Solutions for Woodstock & Oxford County
Buying in town, refinancing a home you've owned for fifteen years, or looking at a property on the edge of the built-up area — the first question is always the same: what does this file need in order to be approved cleanly, and which lender treats it best?
- Home purchases in Woodstock and across Oxford County
- First-time buyer and move-up buyer financing
- Pre-approval with a rate hold before you shop
- Renewals and lender switches at maturity
- Refinancing, debt consolidation and HELOCs
- Self-employed, shift-work and variable income
- Rural and semi-rural properties with well and septic
First-Time Buyers in Woodstock
Woodstock prices remain more attainable than London, which is why so many first purchases happen here. The obstacles are rarely income — they're down payment paper trails, vehicle and student debt inside the qualifying ratios, and buyers who rely on a verbal pre-qualification instead of a properly underwritten pre-approval.
We sort those out before you write an offer, so your financing condition is a formality rather than a risk.
Commuters on the 401 / 403 Corridor
Many Woodstock buyers work in London or elsewhere along the 401. Lenders don't penalise a commute, but the cost of it shows up in the file: vehicle payments and insurance count against your debt service. Before you trade a shorter commute for a bigger house, it's worth modelling the true monthly difference.
Older In-Town Homes and Purchase Plus Improvements
A large share of Woodstock's housing stock predates modern building standards. Knob-and-tube wiring, older oil tanks, aging roofs and undersized electrical service can all affect an appraisal or attract lender conditions.
Purchase Plus Improvements financing lets you roll qualifying upgrades into the mortgage at closing based on the improved value, provided quotes are submitted up front — it has to be arranged before closing, not after.
Rural & Semi-Rural Properties Around Oxford County
Outside the serviced area, the details matter: well potability and flow results, a functional septic system, acreage limits, outbuildings that may carry little lending value, and zoning that reads agricultural rather than residential.
None of that makes a property unfinanceable. It makes lender selection the deciding factor — some lenders finance acreage and a barn without hesitation, others contribute value only for the house and a small parcel.
Renewals, Refinancing & Home Equity
Longtime Woodstock owners frequently hold meaningful equity. That can fund renovations on an older home, consolidate higher-interest debt into one manageable payment, or help a family member with a down payment. Any mid-term move has to clear the prepayment penalty math — sometimes waiting for maturity genuinely is the better answer, and I'll tell you when it is.
Self-Employed and Variable-Income Borrowers
Oxford County runs on trades, transport, agriculture-adjacent services and owner-operated businesses. When declared income understates real cash flow, business-for-self programs and alternative lenders provide a route — paired with a documented plan to return to prime pricing once the notices of assessment support it.
Investment Properties in Woodstock
Rent-to-price ratios in Oxford County can work better than in larger centres. Non-owner-occupied purchases still require 20% down, and lenders differ in how much projected rent they credit toward qualifying — that single difference usually decides whether a deal is approvable.
Why use a broker instead of a bank?
Many lenders, one application
A bank can only offer its own products. A broker compares banks, credit unions and mortgage lenders for your file.
Usually no fee to you
On standard residential mortgages the lender pays the broker. Any fee on alternative or private files is disclosed in writing first.
Terms, not just the rate
Penalties, prepayment privileges and portability are compared up front, so the cheapest rate isn't the costliest mortgage.
Illustrative example
Illustrative example: a manufacturing worker with overtime income
Illustrative example — not a real client. A Woodstock buyer works at a manufacturing plant with a steady base wage plus regular overtime and shift premiums. One lender would only count the base wage, which limits the purchase price. Another lender may average the overtime over two years using T4s and notices of assessment, which could support a higher amount.
How variable income is counted depends on the lender's guidelines, the employment letter and the documented history. Any outcome is subject to approval.
Woodstock mortgage questions
Do I need to be in Woodstock to work with you?
No. The process runs by phone, email and secure document upload, and I meet in person across Oxford County when that's easier. Documents are signed electronically and the closing is handled by your lawyer locally.
Can I finance an older Woodstock home that needs work?
Usually yes. Purchase Plus Improvements financing adds qualifying renovation costs to the mortgage based on the improved value, as long as contractor quotes are provided before closing. Known issues such as knob-and-tube wiring or an old oil tank should be flagged early because some lenders and insurers treat them differently.
Is a well-and-septic property near Woodstock harder to finance?
Not harder, just more specific. Lenders typically want proof the water is potable with adequate flow and that the septic is functional. Acreage, zoning and outbuildings determine which lenders will treat the property favourably.
Are mortgage rates different in Woodstock than in London?
No. Rates and qualification rules are set nationally, not by municipality. What changes locally is the appraisal, since it relies on Woodstock comparables — that matters most for unusual or rural properties.
What credit score do I need to buy in Woodstock?
Roughly 680 or higher gets the best prime pricing, though approvals happen below that with compensating factors like a larger down payment or strong income. Alternative lenders work with lower scores at higher rates, generally as a short-term step back toward prime.
Do lenders count overtime and shift premiums for Woodstock manufacturing workers?
Often, yes, when there's a consistent history. Many lenders want around two years of overtime or shift income, shown on T4s and notices of assessment, and may average it. Some lenders count less or none of it. An employment letter that clearly states base pay, guaranteed hours and the variable components helps. Because treatment varies so much, matching your pay structure to the right lender can make a real difference to how much you qualify for.
Can I get a mortgage while I'm still on probation at a new job?
It can be possible, depending on the lender and your situation. Some lenders will accept an applicant on probation if they're in the same line of work and have a solid history, especially in a permanent, full-time role. Others will wait until probation ends. If you're changing jobs before buying, tell your mortgage agent early so the timing of the offer, the employment letter and the closing date can be planned around it.
Is Woodstock a good place to buy if I commute on the 401 or 403?
That's a lifestyle and budget decision rather than a lending one. Lenders don't reduce a mortgage because of a commute; they look at income, credit, down payment and debts. What a commute does affect is your monthly cash flow and any vehicle payment that counts in your debt ratios. It's worth comparing the full monthly cost of owning in Woodstock, including travel, against the alternatives before you set a budget.
Are older Woodstock homes harder to insure or finance?
Some older homes raise extra questions from lenders and home insurers, such as older wiring, oil tanks, roof age or foundation issues. That doesn't stop a purchase, but it can add conditions. A home inspection during the conditional period, plus an early insurance quote, helps you find out whether repairs are needed and whether a purchase-plus-improvements structure may be an option with the lender.
When should I start comparing options for my Woodstock mortgage renewal?
Around four months before your maturity date is a good time to start. Many lenders can hold a rate for a switch for up to around 120 days. That gives you time to compare your lender's renewal offer against other options. Switching at maturity generally avoids a prepayment penalty, although legal or appraisal costs may apply depending on the lender. Starting early means you have time to decide without pressure.
Also serving communities near Woodstock
Ingersoll · London · Tillsonburg · Thamesford · Norwich · Tavistock — and surrounding Southwestern Ontario communities. Mortgage services are provided remotely and in person; there is no branch office in these locations.
London mortgage services
Examples from London neighbourhoods
Guides & tools
Nearby town pages
Client experiences
Clients across London, Woodstock and surrounding Southwestern Ontario communities have shared their experiences on Google. Read them in full, unedited.
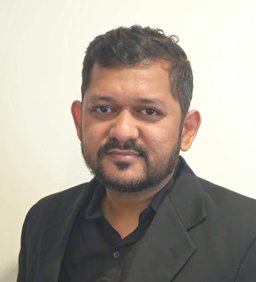
Meet Nandan Bajani
Mortgage Agent Level 1 | Ontario
The Mortgage Firm Inc.
I'm Nandan Bajani of Bajani Mortgage, working with The Mortgage Firm Inc. I serve Woodstock and the surrounding Oxford County communities the same way as every other file on this site — underwrite the situation properly first, then match it to the lender that actually fits.
Meet NandanDiscuss Your Woodstock Mortgage Options
Not just finding a rate. Finding the right mortgage strategy. Book a free, no-obligation consultation.