
Serving Ingersoll, Ontario
Mortgage Broker in Ingersoll, Ontario
Pre-approvals, purchases, renewals and refinancing for Ingersoll and Oxford County, compared across 50+ lenders, including 401 commuters, move-up buyers and semi-rural homes.
- FSRA licensed agent
- 50+ lenders compared
- MBA in Finance
- Based in London, ON
Ingersoll at a glance
- Population
- About 13,600 (2021 Census)
- Growth
- +7.2% from 2016 to 2021
- Region
- Oxford County, on the 401 between London and Woodstock
- Municipal land transfer tax
- None, provincial tax only
- Common buyers
- 401 commuters, move-up families, semi-rural buyers
- Watch for
- Well and septic on semi-rural properties
Sources: Statistics Canada 2021 Census, population centres (Ingersoll 13,607; 12,694 in 2016). Your own approval depends on your file, not the town.
Today's Lowest Rates · Ingersoll
As of October 23, 2026
- Fixed
- 4.34%
- 5-Year term
- Variable
- 3.43%
- 5-Year term
- Prime
- 4.45%
- Bank of Canada
Rates are set by lenders, not by town, and depend on your own file.
Compare all 8 terms & inquire
Ingersoll, Ontario — Daily Update
Compare Today's Mortgage Rates
As of October 23, 2026
Bank of Canada overnight rate 2.25%, prime 4.45%
2-Year
Fixed
4.39%
Big 6 Bank
Variable
—
3-Year
Fixed
4.49%
Canadian Lender
Variable
3.90%
Alterna Savings
5-Year
Fixed
4.34%
Canadian Lender
Variable
3.43%
Canadian Lender
Rates shown are for insured mortgages (down payment under 20%). Conventional/uninsured pricing may differ — contact me for your exact rate.
Rates are illustrative, change daily and are subject to lender qualification. Source: Ratehub.ca public rate table, as of October 23, 2026.
Mortgage services for Ingersoll clients
Swipe for more services →
Access to 50+ lenders — banks, credit unions and mortgage lenders




Big banks · Credit unions · Mortgage lenders
+ 40 more, compared for youBuying or renewing in Ingersoll
Ingersoll sits on the 401 between London and Woodstock, in the middle of Oxford County. That location shapes the mortgage files I see here: commuters buying where their dollar goes further, move-up buyers trading a townhouse for a detached home, and buyers looking at semi-rural properties just outside town.
Ingersoll's housing is a mix of older homes close to the downtown and the Thames River, established neighbourhoods of bungalows and two-storey homes, and newer subdivisions. Outside town, Oxford County farmland and rural lots bring wells, septic systems and larger parcels into the picture.
Many Ingersoll buyers commute along the 401 to Woodstock or London, and many are moving up from a townhouse or semi to a detached home. Homeowners renewing here often want to compare a lender switch, consolidate a car loan, or fund a renovation on an older house.
Mortgage Solutions for Ingersoll & Oxford County
Whether you're buying in town, refinancing a property you've owned for a decade, or looking at an acreage outside the built-up area, the starting point is the same: what does this file actually need to be approved cleanly?
- Home purchases in Ingersoll and surrounding Oxford County
- First-time buyer and move-up buyer financing
- Pre-approval with a rate hold
- Renewals and switches at maturity
- Refinancing, debt consolidation and HELOCs
- Self-employed, farm-adjacent and variable income
- Rural and semi-rural properties with well and septic
First-Time Buyers in Ingersoll
First-time buyers here are frequently choosing between a smaller property closer to London and more space in Ingersoll for a similar payment. Once you've made that call, the financing work is straightforward: verify the down payment's 90-day history, account for existing debt in the qualifying ratios, and hold a rate before you shop.
Move-Up Buyers and Timing Two Transactions
Selling one home and buying another rarely lines up perfectly. Bridge financing covers the gap when your purchase closes before your sale — it requires a firm, unconditional sale agreement, and it's arranged alongside the new mortgage rather than as an afterthought.
If the closings can't be aligned, we look at the alternatives early: a longer close on the purchase, a shorter one on the sale, or financing structured to accommodate carrying both briefly.
Rural & Semi-Rural Properties Near Ingersoll
Properties outside the serviced area bring specifics that trip up a standard urban application: well and septic systems (lenders commonly want potability and flow results, and confirmation the septic is functional), acreage limits, outbuildings that may carry little or no lending value, and zoning that reads agricultural rather than residential.
None of this makes a property unfinanceable — it makes lender selection matter. Some lenders will finance ten acres with a barn without blinking; others cap value contribution at the house and a small parcel.
Commuters Buying Near the 401 Corridor
The Ingersoll–Woodstock–London corridor is popular precisely because of highway access. From a lending standpoint the commute itself is neutral, but the associated costs aren't: vehicle payments and insurance are part of your debt-service calculation. It's worth modelling the true monthly cost of a longer commute against the price difference before committing.
Renewals, Refinancing & Home Equity
Longtime Ingersoll owners often hold substantial equity. That supports consolidating higher-interest debt, funding renovations on an older property, or helping with a down payment for a family member. As always, the mid-term math includes any prepayment penalty — sometimes waiting for maturity is simply the better answer.
Self-Employed Borrowers in Oxford County
Oxford County has a strong base of trades, agricultural services and owner-operated businesses. Where declared income doesn't reflect actual cash flow, business-for-self programs and alternative lenders provide routes forward — with a documented plan to move back to prime pricing when the notices of assessment support it.
Investment Properties
Smaller Oxford County markets can offer more favourable rent-to-price ratios than larger centres. Financing still requires 20% down on non-owner-occupied purchases, and lenders differ in how much projected rent they'll credit toward qualifying — which is usually what determines whether a given deal works.
Why use a broker instead of a bank?
Many lenders, one application
A bank can only offer its own products. A broker compares banks, credit unions and mortgage lenders for your file.
Usually no fee to you
On standard residential mortgages the lender pays the broker. Any fee on alternative or private files is disclosed in writing first.
Terms, not just the rate
Penalties, prepayment privileges and portability are compared up front, so the cheapest rate isn't the costliest mortgage.
Illustrative example
Illustrative example: a move-up buyer commuting to Woodstock
Illustrative example — not a real client. A family owns a townhouse in London and wants a detached home in Ingersoll, closer to one partner's job in Woodstock. Their current mortgage is mid-term, so they look at whether it can be ported to the new home, how a bridge loan might cover the gap between closing dates, and what the prepayment penalty would be if they broke the mortgage instead.
The right option depends on the existing lender's porting rules, the closing dates and qualification under the stress test. Any outcome is subject to approval.
Ingersoll mortgage questions
Can I get a mortgage for a property near Ingersoll with a well and septic?
Yes. Lenders typically want confirmation the water is potable with adequate flow and that the septic system is functional. Some lenders are far more comfortable with acreage and outbuildings than others, so the property details should be reviewed before you finalize an offer.
Do I need a different mortgage for a rural property?
Not a different product, but potentially a different lender. Standard residential mortgages apply to most semi-rural homes. Restrictions appear with large acreage, agricultural zoning, or when significant value sits in outbuildings rather than the house.
How does bridge financing work when I'm selling and buying in Ingersoll?
Bridge financing covers the period between your purchase closing and your sale closing. It requires a firm, unconditional sale agreement and is arranged with your new mortgage. Costs are typically interest for the bridge period plus a modest administration fee.
Is Ingersoll considered part of the London market for mortgage purposes?
Ingersoll is in Oxford County, not Middlesex, but lending guidelines are national — rates and qualification rules don't change by municipality. Appraisers do use local comparables, which matters when a property is unusual for the area.
What credit score do I need to buy a home in Ingersoll?
Most prime lenders look for roughly 680 or higher for the best pricing, though approvals happen below that with compensating factors. Alternative lenders work with lower scores at higher rates, typically as a short-term step back toward prime.
Can I port my mortgage if I sell in London and buy in Ingersoll?
Many mortgages are portable, meaning you may be able to move your existing rate and balance to a new property, sometimes blending in extra funds at a current rate. Porting rules vary a lot by lender: some require both closings on the same day, others give a window of time. You'll also need to requalify for any new money. Check your mortgage documents or ask your lender before listing, because the answer affects your timing and your penalty.
What is a bridge loan, and when would an Ingersoll buyer need one?
A bridge loan is short-term financing that covers your down payment when your new purchase closes before your current home sale. It's usually used when you already have a firm sale agreement. Not every lender offers one, and fees and limits vary. If your closing dates line up, you won't need one. If they don't, it's worth arranging early rather than trying to sort it out in the final week before closing.
Does a rural Oxford County property need a different lender?
Sometimes. Homes on larger lots, or with a well and septic, are financed by many mainstream lenders, but each has limits on acreage, outbuildings and agricultural use. If the property is a working farm or the land is the main value, it may need an agricultural or specialty lender. Confirming the zoning, lot size and water and septic records early helps match you to a lender that fits the property.
Will my commute to London or Woodstock affect my mortgage approval?
No. Lenders don't adjust your approval based on where you work. They look at your income, credit, down payment and debts. A commute can affect your finances, though: a new vehicle loan or lease adds to the debts lenders count, and fuel and insurance come out of your monthly budget. It's worth factoring those in before settling on a purchase price.
Can I refinance an older Ingersoll home to pay for renovations?
Generally, you can refinance up to 80% of your home's appraised value, subject to qualification, and use the equity for renovations or to pay off higher-interest debt. Breaking your mortgage mid-term usually triggers a prepayment penalty, so the decision compares that cost with the benefit. If you only need funds in stages, a HELOC may be another option. Getting quotes for the work first gives the lender a clearer picture.
Also serving communities near Ingersoll
Woodstock · London · Tillsonburg · Thamesford · Dorchester · Norwich — and surrounding Southwestern Ontario communities. Mortgage services are provided remotely and in person; there is no branch office in these locations.
London mortgage services
Examples from London neighbourhoods
Guides & tools
Nearby town pages
Client experiences
Clients across London, Ingersoll and surrounding Southwestern Ontario communities have shared their experiences on Google. Read them in full, unedited.
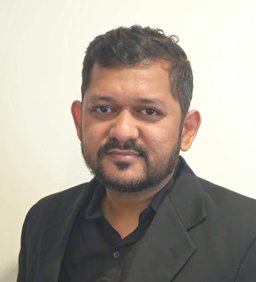
Meet Nandan Bajani
Mortgage Agent Level 1 | Ontario
The Mortgage Firm Inc.
I'm Nandan Bajani of Bajani Mortgage, working with The Mortgage Firm Inc. I serve Ingersoll and the surrounding Oxford County communities with the same approach used everywhere else on this site — underwrite the file properly first, then match it to the right lender.
Meet NandanDiscuss Your Ingersoll Mortgage Options
Not just finding a rate. Finding the right mortgage strategy. Book a free, no-obligation consultation.