
Serving St. Thomas, Ontario
Mortgage Broker in St. Thomas, Ontario
Pre-approvals, purchases, renewals and refinancing for St. Thomas and Elgin County, compared across 50+ lenders, including shift, overtime and self-employed income.
- FSRA licensed agent
- 50+ lenders compared
- MBA in Finance
- Based in London, ON
St. Thomas at a glance
- Population
- About 43,000 (2021 Census)
- Region
- Elgin County, about 30 km south of London
- Big new employer
- Volkswagen PowerCo battery plant, production targeted for 2027
- Municipal land transfer tax
- None, provincial tax only
- Housing mix
- Older brick homes, newer subdivisions, rural acreage nearby
- Common income types
- Shift, overtime, trades and London commuters
Sources: Statistics Canada 2021 Census (population 42,918); PowerCo/Volkswagen announcements, October 2025. Your own approval depends on your file, not the town.
Today's Lowest Rates · St. Thomas
As of October 23, 2026
- Fixed
- 4.34%
- 5-Year term
- Variable
- 3.43%
- 5-Year term
- Prime
- 4.45%
- Bank of Canada
Rates are set by lenders, not by town, and depend on your own file.
Compare all 8 terms & inquire
St. Thomas, Ontario — Daily Update
Compare Today's Mortgage Rates
As of October 23, 2026
Bank of Canada overnight rate 2.25%, prime 4.45%
2-Year
Fixed
4.39%
Big 6 Bank
Variable
—
3-Year
Fixed
4.49%
Canadian Lender
Variable
3.90%
Alterna Savings
5-Year
Fixed
4.34%
Canadian Lender
Variable
3.43%
Canadian Lender
Rates shown are for insured mortgages (down payment under 20%). Conventional/uninsured pricing may differ — contact me for your exact rate.
Rates are illustrative, change daily and are subject to lender qualification. Source: Ratehub.ca public rate table, as of October 23, 2026.
Mortgage services for St. Thomas clients
Swipe for more services →
Access to 50+ lenders — banks, credit unions and mortgage lenders




Big banks · Credit unions · Mortgage lenders
+ 40 more, compared for youBuying or renewing in St. Thomas
St. Thomas draws a distinct mix of buyers: local families who have been here for generations, London commuters looking for more house per dollar, and shift workers in manufacturing and logistics whose income doesn't fit a tidy salary letter.
St. Thomas housing ranges from older brick homes near the downtown core and Talbot Street to newer subdivisions on the city's edges, with rural and acreage properties across Elgin County a short drive away. Many first purchases here are older homes, and lenders may ask for an inspection, an appraisal condition or a holdback for repairs.
Typical buyer profiles include first-time buyers who want a detached home or townhouse, households moving out from London for more space, and Elgin County owners renewing on properties with wells, septic systems or outbuildings. Acreage and rural homes generally need a lender comfortable with the land, zoning and water source, so it pays to check that before you write an offer.
Mortgage Solutions for St. Thomas Buyers & Homeowners
The service list is the same as anywhere — purchases, pre-approvals, renewals, refinances, HELOCs, self-employed and investment files. What changes is which lenders are the right fit once income structure and property type are on the table.
- Home purchases, including older housing stock needing improvement funds
- First-time buyer planning and down payment structuring
- Pre-approval with a held rate before you shop
- Renewals and lender switches at maturity
- Refinancing, debt consolidation and equity take-out
- Shift, overtime, contract and self-employed income
- Rental and multi-unit financing
First-Time Buyers in St. Thomas
Entry-level pricing in St. Thomas has historically sat below London, which is exactly why first-time buyers look here. The practical consequence is that a larger share of purchases are older homes where a lender may require work to be completed, or where a purchase-plus-improvements structure makes more sense than paying for renovations with credit cards after closing.
We'll confirm your down payment documentation, review how any car loan or line of credit is eating into your qualifying room, and set a realistic ceiling before you start viewing.
Shift, Overtime and Variable Income
Manufacturing, warehousing and logistics employment around St. Thomas often means base pay plus significant overtime or shift premiums. Lenders treat that inconsistently: some will use a two-year average of the variable portion, some require a longer history, and some will only count base salary.
Getting this right can move your qualifying amount meaningfully. It comes down to matching your pay structure and documentation — T4s, notices of assessment, an employment letter that actually states the variable components — to a lender whose guidelines recognize it.
Commuting Between St. Thomas and London
A large share of St. Thomas buyers work in London. That's a lifestyle and budget decision rather than a lending one — lenders don't discount a mortgage for a commute — but it does affect what you should budget. Vehicle costs and an existing car loan reduce qualifying room, so it's worth modelling the total monthly picture, not just the mortgage payment.
Mortgage Renewals & Refinancing in St. Thomas
If you bought in St. Thomas several years ago, you may have meaningful equity relative to your original purchase price. That opens options at renewal: shortening amortization, consolidating higher-interest debt, or funding a renovation on an older property.
Approach renewal about four months before maturity so there's time to compare a transfer against your existing lender's offer without any pressure.
Self-Employed & Alternative Lending
Contractors, trades and small-business owners in Elgin County often show low net income after write-offs. Where an A-lender won't work, alternative lenders can underwrite on equity and reasonability, typically with a clear plan to return to prime pricing at the next renewal. That plan matters — an alternative mortgage should be a bridge, not a destination.
Investment Properties in St. Thomas
Lower entry prices and steady rental demand make St. Thomas an active market for small investors. Financing considerations include the 20% minimum down payment on non-owner-occupied purchases, how each lender treats projected rent, and — for anything presented as a duplex — whether the second unit is legal and appraisable as such.
Why Work With a Local Mortgage Broker?
Because the answer to 'can this be financed?' depends entirely on which lender you ask. Working through a broker means the question is asked across a network rather than at one branch — and it means a straight answer on structure, penalties and prepayment terms before you sign.
Why use a broker instead of a bank?
Many lenders, one application
A bank can only offer its own products. A broker compares banks, credit unions and mortgage lenders for your file.
Usually no fee to you
On standard residential mortgages the lender pays the broker. Any fee on alternative or private files is disclosed in writing first.
Terms, not just the rate
Penalties, prepayment privileges and portability are compared up front, so the cheapest rate isn't the costliest mortgage.
Illustrative example
Illustrative example: first purchase of an older St. Thomas home
Illustrative example — not a real client. A couple renting in London wants to buy an older detached home in St. Thomas. The inspection flags an aging roof and windows. Rather than paying for repairs out of pocket after closing, they ask about a purchase-plus-improvements structure, where a lender may add the quoted renovation cost to the mortgage and release it once the work is confirmed.
The approach depends on the lender, the appraisal and the couple's qualification under the OSFI stress test. Any outcome is subject to approval.
St. Thomas mortgage questions
What should St. Thomas homebuyers know about mortgage financing?
Two things stand out locally: older homes may need lender-required work or a purchase-plus-improvements structure, and variable income like overtime or shift premiums is treated very differently from lender to lender. Both are worth sorting out before you make an offer.
Are mortgage rates different in St. Thomas than in London?
No. Rates are set by lenders nationally and depend on your file — credit, down payment, income type, property type and term — not on which Ontario city you buy in. What can differ is which lenders are comfortable with a specific property.
Can I get pre-approved before I start looking in St. Thomas?
Yes, and you should. A pre-approval confirms your realistic range, holds a rate for a defined period, and surfaces any documentation issues while there's still time to solve them.
Does overtime income count toward my mortgage qualification?
Often yes, if you have a consistent history — commonly two years — and the documentation supports it. Some lenders average the variable portion, others require a longer track record. Lender selection makes a real difference here.
Can I buy a rental property in St. Thomas with less than 20% down?
Not for a straight non-owner-occupied rental — those require a minimum 20% down payment. Owner-occupied properties with a legal secondary unit can be a different story, and those files are worth reviewing individually.
Can I buy an Elgin County acreage property with a regular mortgage?
Often, yes, but not with every lender. Lenders look at lot size, zoning, the water source, the septic system and whether the property is mainly residential or agricultural. Many A-lenders will finance a home on acreage when the house is the main use of the property, sometimes valuing only a portion of the land. Before you make an offer, it helps to confirm the well and septic paperwork and check the lender's acreage limits, so the appraisal doesn't come back with surprises.
Are older St. Thomas homes harder to finance?
Not necessarily, but they can raise more questions. Lenders and mortgage insurers may ask about knob-and-tube wiring, oil tanks, roof age or foundation issues, and home insurers may have their own conditions. Sorting these out during the conditional period gives you time to get quotes, adjust the offer or arrange a purchase-plus-improvements structure if a lender allows it.
Can I use the FHSA and RRSP Home Buyers' Plan for a St. Thomas purchase?
Yes. Both programs are federal, so they apply anywhere in Canada, including St. Thomas. If you qualify as a first-time home buyer, you may be able to combine a First Home Savings Account withdrawal with an RRSP Home Buyers' Plan withdrawal toward your down payment. Each has its own eligibility rules and timing, so confirm the details with the Canada Revenue Agency or your financial advisor before you rely on the funds.
I work in London but want to buy in St. Thomas. Does that affect my mortgage?
Lenders don't reduce a mortgage because of a commute. Your approval depends on your income, credit, debts and down payment. What a commute does affect is your budget: a car loan or lease counts against your debt service ratios, and fuel and insurance come out of your monthly cash flow. It's worth running the numbers with and without a new vehicle payment before deciding how much house to buy.
When should I start my renewal if my St. Thomas mortgage matures soon?
About four months before maturity is a sensible time to start. Many lenders will hold a rate for up to around 120 days on a switch, which gives you time to compare your current lender's renewal offer against other options. Switching at maturity generally avoids a prepayment penalty, though there may be legal or appraisal costs depending on the lender. Starting early means you aren't forced to sign the first offer that arrives.
Also serving communities near St. Thomas
London · Aylmer · Port Stanley · Belmont · Dorchester · Ingersoll — and surrounding Southwestern Ontario communities. Mortgage services are provided remotely and in person; there is no branch office in these locations.
London mortgage services
Examples from London neighbourhoods
Guides & tools
Nearby town pages
Client experiences
Clients across London, St. Thomas and surrounding Southwestern Ontario communities have shared their experiences on Google. Read them in full, unedited.
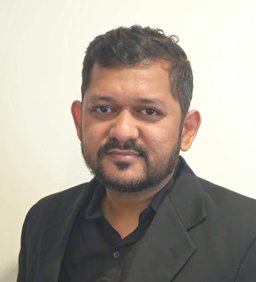
Meet Nandan Bajani
Mortgage Agent Level 1 | Ontario
The Mortgage Firm Inc.
I'm Nandan Bajani of Bajani Mortgage, working with The Mortgage Firm Inc. I help St. Thomas buyers and homeowners get properly underwritten up front, so financing isn't the thing that falls apart after an offer is accepted.
Meet NandanDiscuss Your St. Thomas Mortgage Options
Not just finding a rate. Finding the right mortgage strategy. Book a free, no-obligation consultation.